Out, Back, and Through
The Treasury curve spent seven sessions round-tripping a war and an inflation shock. On the eighth, it broke the range.
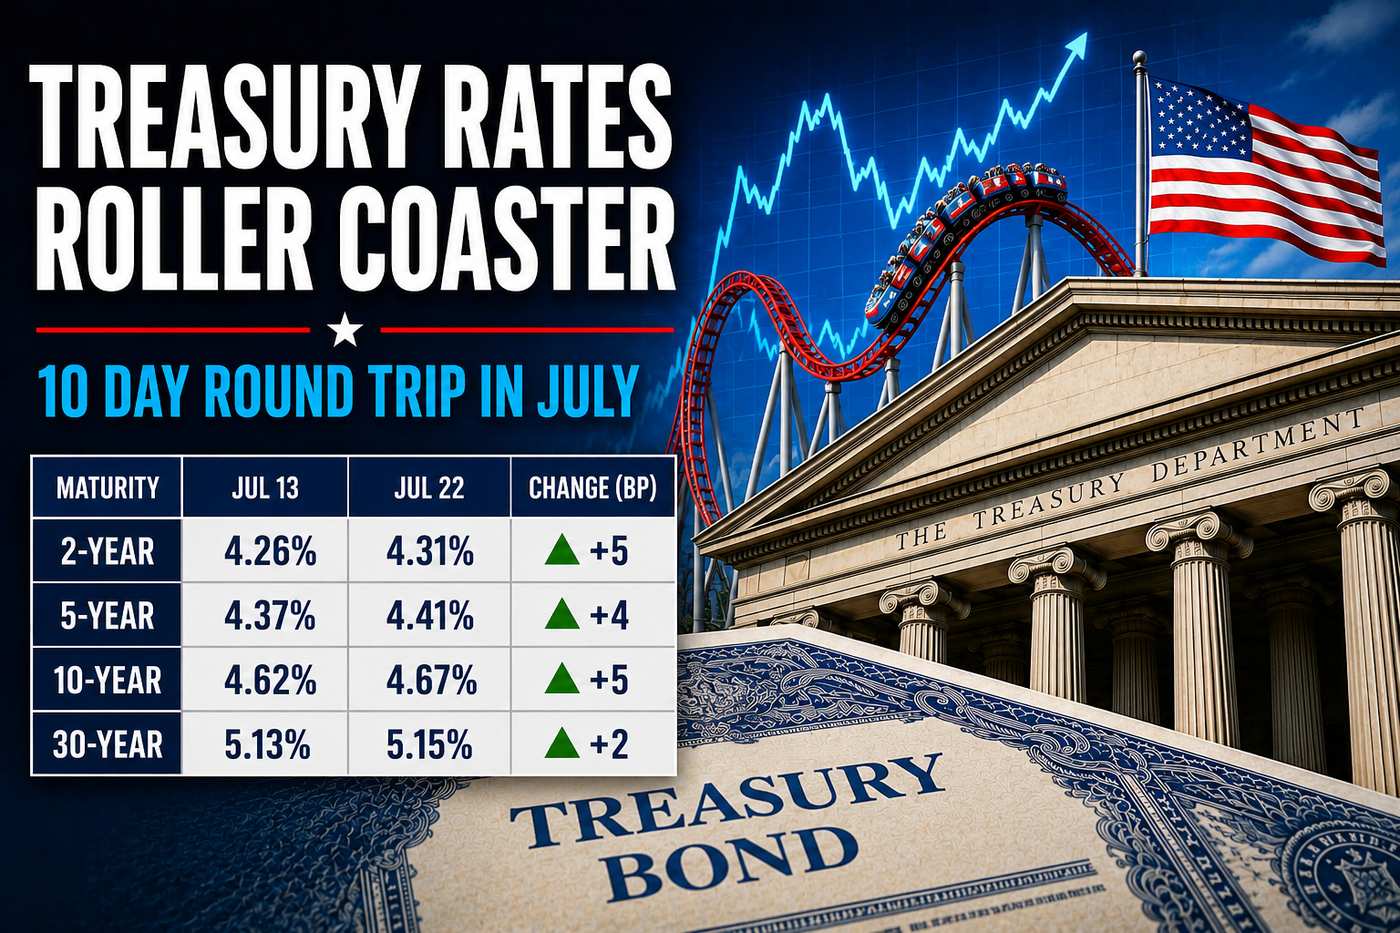
Between Monday July 13 and Wednesday July 22, the Treasury market ran a complete experiment. It sold off, rallied hard on the biggest inflation surprise of the year, gave every basis point back, and then broke to fresh highs.
Here are the four snapshots.
| Date | 2-Year | 5-Year | 10-Year | 2s10s |
|---|---|---|---|---|
| Mon, Jul 13 | 4.26% | 4.37% | 4.62% | 36 bp |
| Wed, Jul 15 | 4.13% | 4.26% | 4.55% | 42 bp |
| Tue, Jul 21 | 4.26% | 4.37% | 4.63% | 37 bp |
| Wed, Jul 22 | 4.31% | 4.41% | 4.67% | 36 bp |
Look at the middle two rows first. July 13 and July 21 are almost the same curve. The 2-year and 5-year are identical to the basis point. That is a round trip.
Then look at the last row. The 10-year at 4.67% is above anything printed in the prior two weeks. The round trip resolved, and it resolved upward.
Leg one: the inflation shock
On July 13 the market was braced for a hot summer. The US-Iran memorandum signed in mid-June had collapsed, with President Trump declaring the deal over on July 8. Oil was climbing and traders were assigning real odds to a Fed hike in July.
Then June CPI landed at 8:30 Tuesday morning and delivered the biggest downside surprise of the year.
Headline CPI fell 0.4% on the month, pulling the annual rate from 4.2% to 3.5% against a consensus near 3.8%. That was the sharpest monthly deceleration in headline inflation since April 2020. Core CPI was flat on the month.
The driver was mechanical: gasoline prices fell nearly 10% in June. That was the delayed dividend of the June ceasefire and the partial reopening of the Strait of Hormuz. June CPI was a photograph of a calmer world that no longer existed by the time it was published.
The front end reacted the way the front end does. Odds of a July hike collapsed from 42% to 17% in a session. Across July 13 to 15 the 2-year fell 13 basis points, the 5-year fell 11, and the 10-year fell only 7.
That differential is the story of leg one. When the short end falls faster, the curve steepens. The 2s10s spread widened from 36 basis points to 42. Traders priced a Fed with room to wait while leaving their long-run inflation view intact.
Leg two: the war reasserts itself
The relief lasted two days.
On the same Tuesday the CPI data was cooling the front end, US Central Command was reimposing a naval blockade on Iranian ports. Strikes continued Wednesday. By Monday July 20, following the deaths of three US service members, the President warned Tehran would be held responsible. Brent settled at $89.22. That same day the Houthis declared a maritime embargo against Saudi Arabia.
From July 15 to July 21 the move reversed almost perfectly. The 2-year rose 13 basis points, the 5-year rose 11, the 10-year rose 8. Every basis point of the CPI rally was returned. The 2s10s spread flattened from 42 back to 37.
Leg three: the second chokepoint
Wednesday July 22 is where the pattern broke.
Brent rose nearly 5% to touch $95.24, the first print above $95 in roughly six weeks. WTI gained close to 4% to $87.45. The trigger was not another strike on Iran. Eleven nights of those had already failed to move the market. The trigger was geography.
Bab el-Mandeb is the strait connecting the Red Sea to the Gulf of Aden. Roughly 2.5 to 3.5 million barrels of Saudi crude leave Yanbu through it every day. With Hormuz effectively closed since late February, Bab el-Mandeb had become the main relief valve for the barrels that could no longer transit the Gulf. The Houthis emailed global shipping companies warning them against loading cargo at Saudi ports.
One threatened chokepoint is a supply problem. Two at once is a different category of problem, because there is no third route to price.
Yields moved accordingly. The 2-year rose 5 basis points to 4.31%, the 5-year rose 4 to 4.41%, the 10-year rose 4 to 4.67%, its highest since May. The 30-year rose only 2, to 5.15%. The average 30-year mortgage climbed to 6.75%, matching its high for the year.
Note which end of the curve led. The 2-year outran the 10-year, and the 30-year barely moved. That is a market pricing a Federal Reserve response, not a fiscal or term premium story. And the 2s10s spread closed at 36 basis points, exactly where it sat on July 13.
The market has now completely unlearned the CPI report.
What the curve is actually saying
Net of everything, from July 13 to July 22 the 2-year is up 5 basis points, the 5-year up 4, the 10-year up 5. A modest parallel shift higher after enormous two-way volatility.
That understates what happened. The market received the best inflation news in four years and the worst supply news in six weeks, weighed them, and concluded the supply news mattered more.
There is one important qualifier, and most commentary is skipping it. The Bab el-Mandeb blockade has been announced, not executed. MarineTraffic counted 73 vessels transiting the strait on Tuesday, only slightly below Monday, alongside four verified U-turns near the Gulf of Aden. The strait is open. Traffic is broadly holding.
What the oil market is pricing is a threat, not a measured loss of barrels. That distinction matters, because threat premiums have historically decayed. Saudi Arabia suspended crude shipments through Bab el-Mandeb in August 2018 after Houthi attacks damaged two tankers, then resumed within weeks.
The risk case is equally clear. A vessel actually struck, or a sustained drop in transit counts, converts a risk premium into a supply story. There is no obvious third route.
The week ahead
The calendar is dense and stacked at the back end.
Tuesday, July 28. Conference Board Consumer Confidence. Normally second tier. Not this month. With the national average for gasoline above $4.00 a gallon, up from $3.87 a week earlier, this is the first read on whether energy costs are reaching household expectations. That is the transmission channel the Fed genuinely fears.
Wednesday, July 29. The FOMC decision. The dominant event. The Committee has June CPI in hand and market pricing for a July move collapsed after that report, so the action is in the statement language and the press conference. The question every desk is asking is whether the Committee treats the oil shock as a relative price change to look through, or as a threat to expectations requiring a preemptive response. A second chokepoint under threat makes the look-through argument harder to make.
Thursday, July 30. Q2 GDP and June PCE. Landing the day after the decision, which is awkward sequencing. PCE is the Fed’s preferred gauge. If it confirms the CPI cooling, the September hike currently priced near 68% comes under pressure. If it diverges, the front end has more repricing to do.
The Bank of England and the Bank of Japan also meet that week, which matters more than usual for Treasuries given how much cross-market flow has driven the long end this year.
What resolves this
Three things would settle the direction.
Transit counts at Bab el-Mandeb. This is the single highest-value number nobody is watching. If daily counts hold near 73 through the week, the premium is theoretical and should decay. If they fall meaningfully, or a vessel is struck, the premium becomes a supply story and yields go with it.
PCE against CPI. The two series weight shelter and health care differently. A divergence leaves the Committee without a clean read into September.
Any credible de-escalation. The June ceasefire took roughly 10% off gasoline in a single month. A second one would do it again, and the front end would move fast.
Until one of those lands, the 10-year has broken out of its two-week range and is sitting at 4.67%. The burden of proof has shifted to the people arguing this is temporary.
Yield data: US Department of the Treasury daily par yield curve rates, cross-checked against the Federal Reserve H.15 constant maturity series. This article is general market commentary, not investment advice. Verify all figures independently before acting on them.
Billy Lee, CEO of Great White Financial, is a sportsman, businessman, artist, speaker, writer, and producer.
Billy is the Founder of the Wellness Institute for Economic Growth and Kairos Athletics.